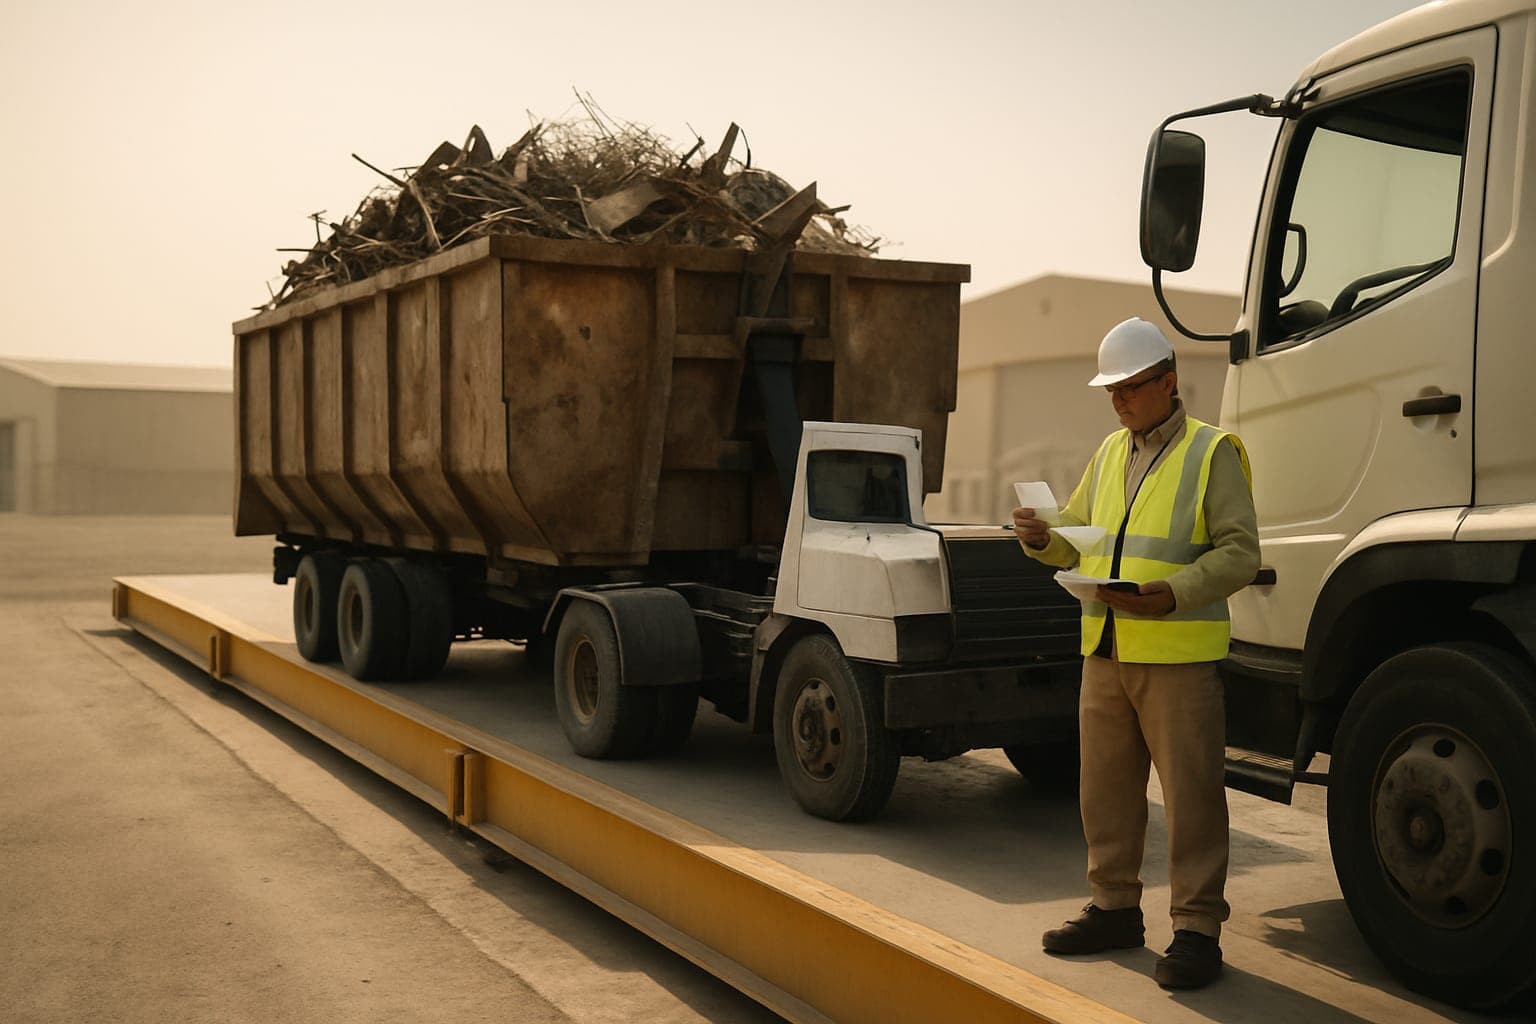
Scope 1 and 2 measurement and disclosure are already binding under Federal Decree-Law No. 11 of 2024, whose full compliance date fell on 30 May 2026. Scope 3, including Category 5 waste generated in operations, is widely expected to follow from 2027, but no MOCCAE instrument confirms that yet. The practical task now is evidence: weighbridge-backed tonnages, treatment method per load, and five years of retrievable records.
Where does UAE Climate Law Scope 3 waste reporting actually stand today?
Federal Decree-Law No. 11 of 2024 on the Reduction of Climate Change Effects was issued on 28 August 2024 and entered into force on 30 May 2025, with a one-year adjustment period under Article 18 running to 30 May 2026. It is the first binding corporate climate accountability law in the region. It obliges entities to register on the national MRV system, build a Scope 1 and 2 inventory, submit annual reports to MOCCAE, file a greenhouse gas reduction plan, and carry out a climate risk assessment covering physical and transition risk.
Scope 3 is not in that list. Every source we have seen that puts Scope 3 in 2027 is advisory commentary rather than a published instrument. Zevero's 5 June 2026 guidance says plainly that a 2027 Scope 3 requirement is not yet confirmed in law and should be treated as expected rather than certain. Oren's March 2026 guide frames it differently again, suggesting Scope 3 may be required for certain sectors or encouraged as best practice. Treat 2027 as a planning assumption, not a legal date.
Even the Scope 1 and 2 timetable is less settled than the headlines suggested. Ropes & Gray reported on 10 April 2026 that MOCCAE representatives had indicated the deadline was expected to be extended pending a technical guidance document that had not been published. Crowe UAE, writing on 2 July 2026, simply treats the deadline as passed and says attention has moved to the accuracy, consistency and credibility of reported data. The London Reporting Academy has gone further, arguing that the Article 18 transition date is not by itself evidence that every UAE legal entity shared one filing deadline, because Article 6 duties attach to Sources determined by MOCCAE together with the relevant competent authority. Four reputable firms, four readings. If you are waiting for a clean answer before you start collecting data, you will wait past 2027.
Why is waste the first Scope 3 line you can control?
Most Scope 3 categories depend on data you do not own. Purchased goods emissions sit with your suppliers. Business travel sits with an agency. Waste is different, because you generate it, you pay someone to move it, and that payment already produces a document. The GHG Protocol's Scope 3 Technical Guidance makes the point itself in Chapter 5: because many waste operators charge according to disposal method, the treatment split can be collected from the waste bill. That single sentence turns better paperwork from housekeeping advice into standard-mandated practice.
The second reason is retention. Federal Decree-Law 11/2024 requires supporting data to be kept for at least five years and made available to MOCCAE on request. A skip volume estimated by a driver does not survive that test. A dated transaction record naming a licensed counterparty, a material, a tonnage and a destination does. If you are already selling recoverable material rather than paying to dispose of it, you are halfway to a defensible file. More on the regulatory backdrop sits in our regulation coverage.
Which duty applies to you: the general law, the large-emitter registry, or the Abu Dhabi system?
Three regimes get mixed together in secondary commentary, and conflating them causes real compliance errors. Cabinet Resolution No. 67 of 2024 on the National Carbon Credit Registry is the one most often misapplied. It bites only on Entities of Huge Carbon Emission, defined as 0.5 million tonnes of CO2 equivalent or more per year across Scope 1 and 2 combined. That is a refinery or a large cement or aluminium operation, not a scrap trader in Al Quoz or a fit-out contractor in Dubai Industrial City.
| Instrument | Who is caught | Core duty | Key date |
|---|---|---|---|
| Federal Decree-Law 11/2024 | Public and private entities generating emissions, free zones included, no size or sector threshold in the text | MRV registration, Scope 1 and 2 inventory, annual report, reduction plan, climate risk assessment, five-year data retention | In force 30 May 2025; compliance date 30 May 2026, with extension reported as expected in April 2026 |
| Cabinet Resolution 67/2024 | Entities at or above 0.5 MtCO2e per year, Scope 1 and 2 combined | Register with the National Carbon Credit Registry, ISO 14064-aligned inventory, verification by a MOCCAE-approved verifier | Registration deadline 28 June 2025; voluntary participation below the threshold |
| Environment Agency Abu Dhabi MRV | Facilities in Abu Dhabi emirate | Annual facility-level Scope 1 report on an EAD template, one report per facility, filed through the EAD portal | 31 March each year |
Two further corrections worth banking. Free zone status is not an exemption under the federal law, so a JAFZA, Hamriyah or KEZAD entity is in scope on the same basis as a mainland one. And voluntary ESG reporting does not discharge the duty. An existing GRI or CDP submission is a communications asset, not a compliance filing.
How do you turn a disposal record into a MOCCAE-ready number?
The calculation is arithmetic, not modelling
Category 5 covers landfill, incineration, recycling, composting and wastewater treatment. Under the average-data method, you multiply total mass of waste in tonnes by the proportion treated by each method, then by an emission factor in kg CO2e per tonne for that method. Nothing in that formula is difficult. The two inputs that fail are the mass, because it was estimated, and the split, because nobody recorded which load went to a landfill and which went to a waste-to-energy plant. Where recovered plastic film ends up matters for both lines, as our note on Warsan Phase 2 and Dubai film streams sets out.
The factor question has no clean UAE answer yet
The GHG Protocol names national inventories as a legitimate factor source. The only MOCCAE-published waste emissions dataset we have been able to locate is the National Air Emissions Inventory Report, first published in 2019 with 2015 as its base year. That is roughly a decade old on base year and should not be presented as current national practice. Underneath it sit the IPCC 2006 Guidelines and the EMEP/EEA Air Pollutant Emission Inventory Guidebook 2023, chapter 5.A on solid waste disposal, which flags landfill gas recovery as a methane mitigation measure. That is why a site-specific factor can diverge sharply from a default.
We have not been able to confirm whether the Integrated Emission Quantification Tool, launched on 12 December 2023 and reachable at mrv.ae, exposes a Category 5 waste module or a UAE-specific factor set to reporting entities. If it does not, the honest position for a 2027 preparer is that you will apply a recognised international default and disclose which one and which version. Auditors accept a documented default. They do not accept an undocumented one.
What must your waste contractor put on every invoice?
Rewrite your collection contract before the next reporting cycle, not after a verifier queries it. These are the fields that make a waste bill usable as emissions evidence:
- Net tonnage per collection, taken from a weighbridge, not a container volume converted by an assumed density.
- The weighbridge ticket reference number, so the invoice line can be traced back to a physical measurement.
- Material description per load, split at least to the categories you report on: mixed construction, metals, plastics, wood, paper, glass, organic.
- Treatment method for that specific load: landfill, waste to energy, material recycling, composting or anaerobic digestion.
- Named destination facility and its licence or permit reference.
- Collection date and vehicle or manifest reference.
- The hauler's trade licence and environmental permit number, plus the emirate that issued it.
- Your own generator reference, so multi-site portfolios can be consolidated without guesswork.
- Where material is sold rather than disposed of, the sale price and the buyer identity.
- A statement of any onward transfer, because a load that leaves a transfer station for a different treatment route changes your split.
Registration on the national system runs through an administrator account with data-provision and validation roles assigned separately, then approval from the relevant emirate-level focal point. Get the invoice fields agreed before you assign the validation role to someone, because that person will be asked to stand behind the numbers.
Is material sold for recycling Category 5 waste at all?
This is where good intentions produce audit findings. GHG Protocol Chapter 5 sets out circumstances in which recycling belongs in a different category entirely. Material you purchase with recycled content carries the upstream recycling emissions inside its cradle-to-gate factor, which places it in Category 1, purchased goods and services. End-of-life treatment of products you sold sits in Category 12. Surplus stock or offcuts sold into reuse through a marketplace may not be waste in your inventory at all, while being an input in your buyer's.
Practically, that means a procurement manager and a sustainability manager need to agree the boundary in writing before either files anything. Double counting a sold aluminium extrusion offcut as Category 5 waste and as your buyer's Category 1 purchase is not a rounding error, it is a methodology failure that a verifier will name. Listings that carry material type, tonnage and a verified counterparty from the outset make the boundary decision documentable, which is part of why we insist on KYC before a transaction closes. You can see how the material is described across the other category on the marketplace.
Why will estimated skip weights fail independent assurance?
Reported data under the federal law is subject to third-party verification by accredited auditors. A verifier tests three things: does the number reconcile to a source document, is the method applied consistently across periods and sites, and can the entity reproduce the calculation from retained records. An estimated skip weight fails the first test immediately. A tonnage that changes when you switch haulers, with no change in activity, fails the second. A spreadsheet whose author left the company fails the third.
The cost asymmetry is stark. Polaris put a minimum-viable emissions inventory and policy at under AED 30,000 as a one-off in its 10 May 2026 note, an advisory estimate rather than a tariff. Administrative fines under Articles 15 and 16 run from AED 50,000 to AED 2,000,000 per violation, doubling to as much as AED 4,000,000 for a repeat violation within two years. There is still no UAE carbon tax, and credits remain tradable through the UAE Carbon Alliance, so the financial exposure today is penalty exposure, not carbon price exposure.
One more point on sequencing. Polaris describes an expected first implementation wave in cement, aluminium, refineries, petrochemicals and steel, plus large energy, utilities and commercial real estate portfolios, with professional services following. Ropes & Gray separately expects national thresholds resembling Abu Dhabi's once technical guidance lands. If you supply any of those sectors from Mussafah, Al Sajaa or Ras Al Khor, expect their procurement teams to ask for your waste and material data well before MOCCAE asks you directly. Our FAQ covers how transaction records are stored and retrieved on the platform.
Frequently asked questions
Is Scope 3 reporting mandatory in the UAE in 2027?
Not as of September 2026. Scope 1 and 2 measurement and disclosure are binding under Federal Decree-Law 11/2024, but no published MOCCAE instrument has made Scope 3 mandatory. Advisory firms including Zevero and Polaris expect a Scope 3 extension around 2027, and Zevero states explicitly that this is expectation rather than law. Plan for it, do not cite it as a legal deadline.
What emission factor should I use for waste sent to landfill in the UAE?
There is no confirmed MOCCAE-published kg CO2e per tonne factor set for waste treatment that we have been able to verify. The only MOCCAE waste emissions dataset we located is the 2019 National Air Emissions Inventory Report, which uses 2015 as its base year. Until federal technical guidance lands, apply a recognised international default from the IPCC 2006 Guidelines or an equivalent inventory, and disclose the source and version in your submission.
What should a waste collection invoice show for carbon reporting?
At minimum: net weighbridge tonnage per collection with the ticket reference, material description per load, treatment method for that load, the named destination facility and its licence number, collection date, and the hauler's trade licence and environmental permit. The GHG Protocol's Scope 3 guidance expressly allows the treatment split to be taken from the waste bill, so the invoice is a legitimate primary source if it carries these fields.
Does selling scrap metal count as Scope 3 waste?
Not automatically. GHG Protocol Chapter 5 describes circumstances where recycling falls outside Category 5, and material sold into reuse or remanufacture may sit in your buyer's Category 1 rather than your Category 5. Agree the boundary with your counterparty in writing and document the reasoning, because mis-slotting sold tonnage across categories is a common assurance finding.
What is the fine for failing to report emissions under the UAE Climate Law?
Administrative fines under Federal Decree-Law 11/2024 range from AED 50,000 to AED 2,000,000 per violation. A repeat violation within two years can be doubled, reaching AED 4,000,000. Those figures come from Articles 15 and 16 as reported by the Library of Congress Global Legal Monitor in June 2025 and by PwC Middle East.
How long must I keep emissions and waste records in the UAE?
At least five years, available to MOCCAE on request, under Federal Decree-Law 11/2024. That retention rule is what makes dated transaction records valuable, because an estimate reconstructed years later will not satisfy a verifier. Store weighbridge tickets, invoices and counterparty identity documents together for each reporting period.
Comments(0)
Sign in to join the conversation.